

A few weeks ago, I successfully concluded my investment in Warner Bros. Discovery (WBD 0.00%↑). As I proclaimed in my last WBD post (now without paywall), on November 19th, I sold my substantial position (approximately 10% of my portfolio) at a profit in the low three digits after the fair value of $24 was reached.

In my sum-of-the-parts analysis at the end of August (now without paywall), I had calculated this value for WBD shares in the following post - just before Paramount made an offer at this very price that David Zaslav rejected.

I am on the sidelines now, but I have decided to write a concluding commentary on Warner Bros. Discovery shares nevertheless. The unfolding bidding war is exciting for the remaining shareholders, but I also think it offers valuable lessons in how we should behave as investors, regardless of the investment case.
Did I make an expensive mistake?
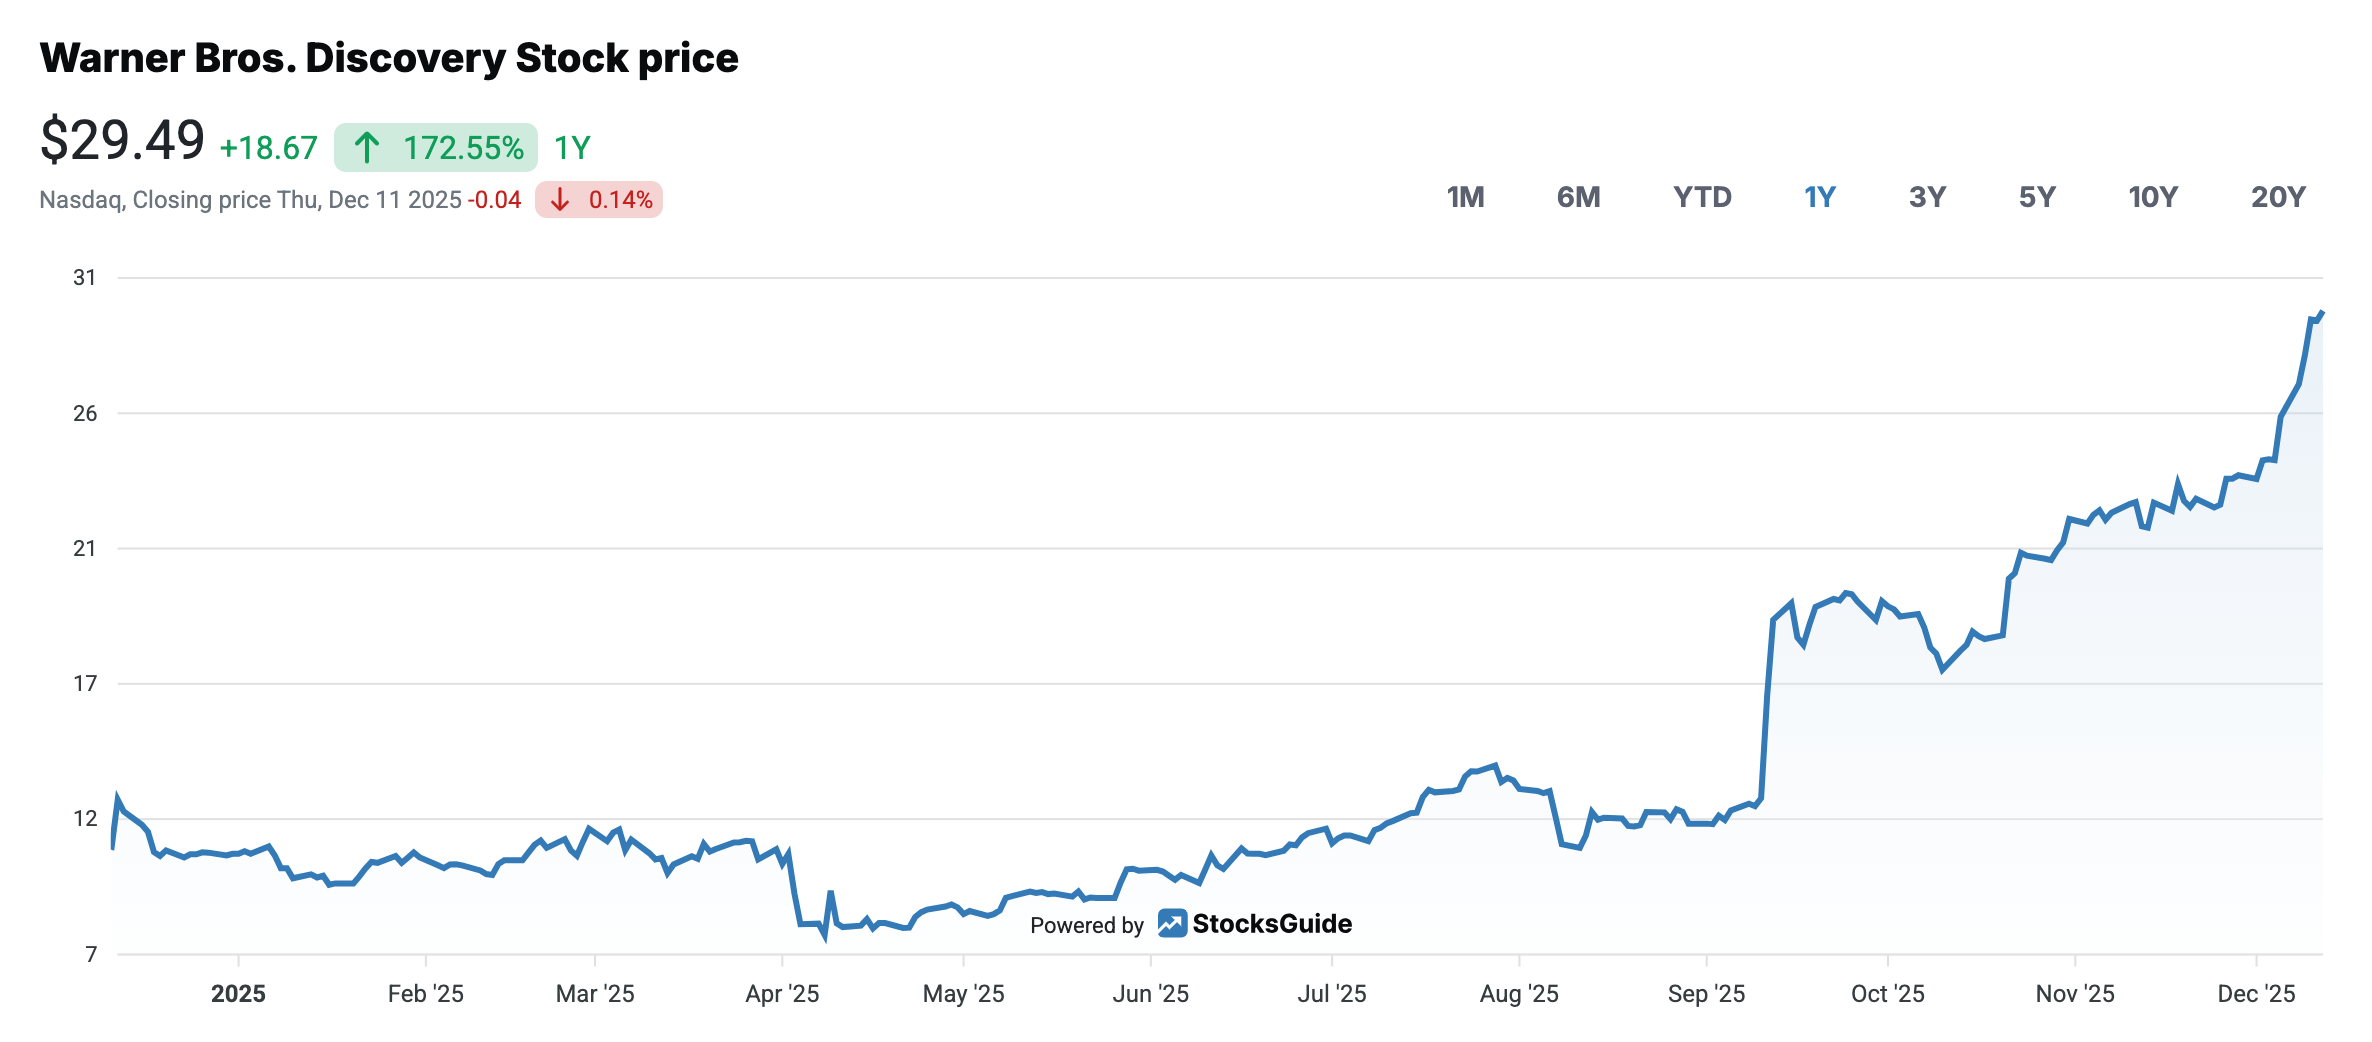
Recently, I’ve been asked several times if I’m upset about selling my WBD shares at the wrong time, just days before the Netflix intended takeover announcement on December 5 and Paramount’s subsequent hostile takeover bid on December 8. Paramount is now offering $30 per WBD share in cash.
So in fact, I missed out on a further 25% increase in the share price by exiting too early.
But was that really a mistake?
First, my sale was simply the consequent implementation of my exit strategy. As a reminder:
„Yes, I really think there could be a bidding war for WBD in the coming weeks. Of course, one could speculate that the price will reach $30 at the end of a takeover battle. I don’t consider that unlikely. Nevertheless, I am acting differently now. After more than 3 years, I am happy that my investment case has finally paid off, and I would actually sell now with a nice three-digit profit as soon as the fair price I calculated of $24-$25 per WBD share is paid.“
Nevertheless, I misjudged Netflix’s management at the time.
„I consider the likelihood of a Netflix offer at a strategic price to be quite low.“
To this day, I have difficulty understanding why Netflix is willing to pay such a high price for Warner Bros.
Let’s not forget that, at approximately $27.75 per share, or an enterprise value of nearly $83 billion, Netflix would not be acquiring the entire WBD group, but “only” its streaming and studio activities called Warner Bros. after the announced split of WBD.
A truly strategic price that is an outgrowth of the AI hype
In my sum-of-the-parts analysis, I calculated an enterprise value of just under $58.5 billion for this Warner Bros. business, based on its earnings potential. I assumed a fair EBITDA multiple of 13 and EBITDA of $4.5 billion.
The valuation that Netflix is now offering is twice as high (an EBITDA multiple of 27.5 with EBITDA expectations of only $3 billion for 2026). This can only be justified by their desire to realize synergies worth billions.
This will require implementing huge cost-cutting programs, i.e., laying off thousands of employees, based on the assumption that the vast potential of Warner’s content library can be monetized just as successfully with far fewer staff in the age of AI.
As a movie lover with a nice home theater, I’m horrified at the thought of AI-written scripts for future D.C. films or HBO series generated by Nvidia GPUs in a CoreWeave data center using AI avatars of Hollywood stars instead of filming in real locations.
However, this strategic price will only pay off for Netflix shareholders if the company successfully implements such an AI vision of the future film industry. To me, this offer for Warner Bros. at this price is another example of the current AI hype. This hype has now taken hold of the media industry, leading to overpriced offers from Netflix and Paramount for Warner Bros.’ iconic franchises.
Skepticism at Netflix is warranted
Even if Gen AI delivers technology that can generate flawless films in a few years, I am convinced that consumers will not be enthusiastic about this new form of storytelling. Therefore, Netflix’s optimistic calculations for resulting synergies worth billions will not work out. Producing first-class entertainment, as Warner Bros. and HBO have done for decades, will remain very labor-intensive in the future, albeit with AI support.
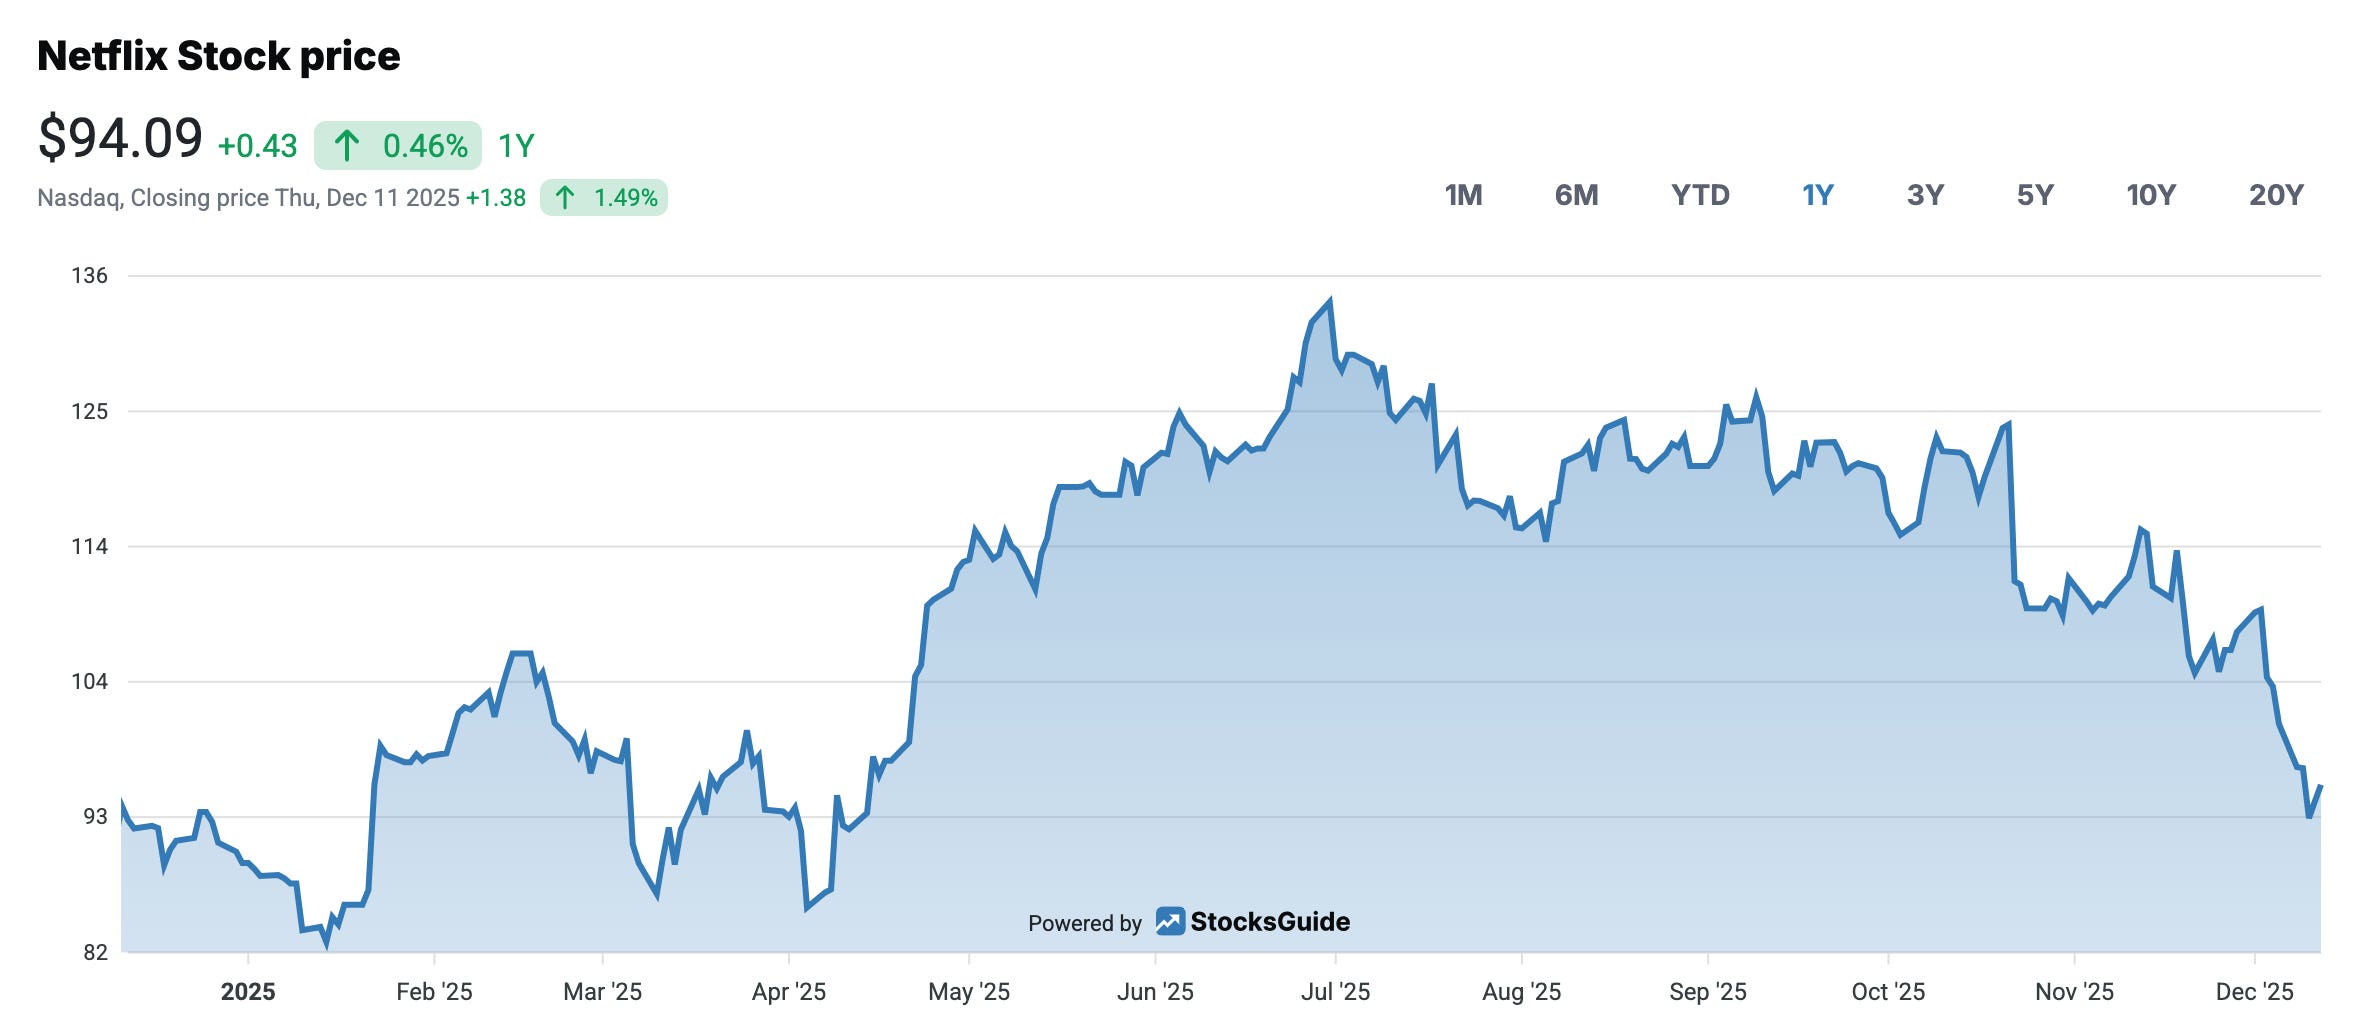
Apparently, the financial market is just as skeptical about the takeover at this price as I am. Netflix shares continued to plummet after the announcement. The stock has lost nearly 20% over the past month, and the correction since its midyear highs has now reached almost 30% . This means that market capitalization has fallen from over $560 billion to $430 billion.
Netflix will have to take on significant debt to finance the acquisition. Specifically, there is talk of long-term debt financing of $50 billion. Even considering the strong free cash flow, which rose to $9 billion before the acquisition, this is an awful lot of money.
Once the acquisition is complete, Netflix’s previously strong balance sheet will be a thing of the past. The smooth repayment of the debt in the coming years depends on whether cash generation across the entire group works as specified in the M&A playbook.
I wouldn’t bet on it. After all, why would the investor community grant the future Netflix group, including Warner Bros., such a high valuation as in the past? Even after the significant decline in its share price, Netflix stock is trading at a free cash flow multiple of nearly 50. This does not align with a growth profile of 10-15% per year and an FCF margin of around 20%.
The more I think about it, the more I wonder why the conservative Netflix management is suddenly taking such risks. Is this acquisition necessary because ideas for organic growth are running out after the password crackdown and introduction of ad-supported subscriptions? I believe that internally, they saw the risk of significant slowdown in organic growth from 2026 onward, which could have caused the share price to plummet. Of course, the acquisition can now avoid this discussion about flattening growth.
But there’s also the considerable risk that the U.S. competition authorities will ultimately block Netflix’s acquisition of WBD after lengthy negotiations. The deal will certainly need Donald Trump’s support to go through. Above all, Trump wants to ensure that CNN is included in the sale and gets a different, less critical management.
However, the current Netflix offer does not include CNN, meaning another stumbling block must be removed. In any case, over the next 12-18 months, a large part of Netflix management’s energy will have to be devoted to successfully completing this M&A deal. Other initiatives will have to take a back seat, for better or worse. The ultimate success is questionable.
Is it all just a bluff?
In my view, the framework conditions and price of this deal are unfavorable for Netflix. In fact, one might believe that Netflix management is just trying to make the WBD acquisition by Paramount more expensive in order to delay the emergence of a strong competitor.
Could Netflix itself not necessarily expect the deal to be completed successfully?
This theory is contradicted by the unusually high reverse breakup fee of $5.8 billion that Netflix would have to pay WBD if the transaction were not completed for reasons not attributable to WBD (e.g., failure to obtain approval from the regulators). That is a significant amount of money for Netflix and corresponds to over 50% of its annual free cash flow.
Ultimately, though, this is all pure speculation. I cannot seriously assess the real motives behind Netflix’s offer or what will ultimately happen. I don’t dare predict whether Netflix or Paramount will succeed with their offer or if regulatory reasons will lead to a totally different dissolution of the current WBD group.
However, I predict that neither Netflix nor Paramount will create sustainable shareholder value with this deal, regardless of the outcome of this bidding war.
Congratulations to all current WBD shareholders who have held on until now and can sell their shares for around $30. In my view, there is no good reason for fundamentally driven investors to hold onto the shares at this point. Any higher offers that come in now are purely exaggerated, driven by FOMO on the part of the players, as well as fueled by short-term speculators.
How do I feel about the lost profits?
The question remains whether I am annoyed that I sold too early and thus missed out on even higher profits. In fact, my WBD position, which I sold a few weeks ago for around 100% profit (average purchase price of $12 and sale price of $24), would now be up by more than 150% (fictitious sale price of $30).
One might think that would be an additional 50% profit. However, that’s the wrong way of thinking. From my exit point of view, I could have achieved an additional 25% in the short term (from $24 to $30) - no more, no less.
Missed profits are a source of frustration, especially for inexperienced investors. I’m not sure if it’s due to my experience or my advanced age, but I’m unfamiliar with this frustration. As an experienced investor, you learn to recognize when it’s time to take profits. Hoping for ever-rising prices is never a good strategy. I previously wrote down the thoughts on my value-based exit strategy here:

When deciding on a possible exit, never forget to consider if the financial resources available from a sale could be better invested elsewhere. I recognized the opportunity to invest in three new companies in recent months and I needed funds to build these positions. You can read about the investment cases for UiPath, Elastic, and Upwork here:


In the case of Upwork and UiPath, I entered at a very opportune time, as my initial positions are already up 20% and 50% after one and three months, respectively. These book profits could certainly be offset against the lost profits from the WBD shares. The best part is that these early price gains are fundamentally justified, while further gains with WBD, which is now fairly valued, are not.
Freeing up capital for new investments is just as important as considering whether it makes sense to increase investments if the price of some stocks in the portfolio moved in the wrong direction despite good fundamental performance.
In October and November, I increased my positions in Angi and IAC at favorable prices after these stocks came under selling pressure. Since then, the tide has turned, with Angi recovering 30% and IAC 20% in recent weeks from their lows.
Reflecting on my investment in WBD, I would like to remind you that I only made a substantial profit because I had the funds and appetite to buy more shares at a time when few other investors wanted them.
Remember that in April 2025, the stock was available for less than $8, and my WBD position was down 30%. Buying more or reducing the price was an equally important and correct decision back then that paved the way for a very successful exit. Now, I’m just happy about the successful investment. Anger over lost profits is an inappropriate, negative thought that I don’t allow myself to entertain.
Conclusion
Lost profits after closing an investment are part of an investor’s life. As long as you made an informed decision and had good reasons for exiting, you shouldn’t be upset about this.
When deciding on a possible exit, consider whether freed-up funds could be invested more promisingly elsewhere. You can do this through exciting new investments or by increasing your high-conviction positions - but only if you are absolutely convinced that they are undervalued.
*Disclaimer: The author and/or affiliated persons or companies own shares in UiPath, Elastic and Upwork. This article represents an expression of opinion and does not constitute investment advice.
Thanks for this article Stefan. It’s so interesting to see the different thought processes.
One can learn from your perspective and I appreciate these kind of articles.
Keep it like it that!
Hi Stefan,
you mentioned a lot of fair points to criticize.
Especially the balance sheet of Netflix would be heavily loaded with debt as you pointed out.
However, I would add that the moat of Netflix would increase given the Crown Jewels of WBD added to their portfolio.
That means that they could raise subscription prices without losing too much of their users.
Question I asked myself:
Would I cancel my subscription if they hike subscription fees by 25% (random number)? Probably not because I would not have better options out there.
Disney does not have many blockbuster shows and is more focused on Disney movies for families and kids and on Marvel franchises.
Amazon’s content library does also not offer the same amount of quality as Netflix.
So there would be streaming giant without much competition.