


Twelve months ago, I published a widely read article about the AI bubble and its impact on the tech stock market. In it, I described three key “proof points” for the existence of this bubble. These were:
Scarcity prices are being paid for AI chips.
Creative accounting by LLM providers,
The AI gold rush in the VC industry
You can read the article here:

So far, my concerns have proven to be unfounded. The first three quarters of 2025 have almost passed, and there is still no sign of the predicted AI crash. The AI rally seems to be unstoppable.
In fact, Nvidia NVDA 0.00%↑ has solidified its position as the world’s most valuable company, with its market capitalization increasing by over 30% since the beginning of the year, reaching $4.3 trillion USD. Pre-market valuations for OpenAI have risen from $157 billion just 12 months ago to an estimated $500 billion today.
The staggering sums involved in this AI gold rush are growing larger and larger, far surpassing anything the business world has ever seen. At least, that’s what the headlines suggest:
The Stargate project plans to invest $500 billion (primarily from Oracle, Softbank, and OpenAI) in AI data centers in the U.S.
Nvidia plans to invest $100 billion in OpenAI. Initially, $10 billion in cash will flow to the ChatGPT manufacturer. In return, Nvidia will receive 2% of OpenAI’s non-voting shares, confirming its $500 billion valuation.
OpenAI plans to invest over $1 trillion in the coming years (WSJ).
These gigantic headlines in recent weeks and months have led to record-breaking price increases for the companies involved, especially Nvidia and Oracle.

Given the current market sentiment, investors seem satisfied that investments in AI infrastructure are growing larger and larger, which they see as a clear indication of AI’s triumph.
Hardly anyone is asking critical questions, yet the latest AI developments raise more questions than they answer. That’s why I’ve compiled my observations and open questions on this topic here.
You’ll see that this financial engineering is quite adventurous. But don’t worry. At the end of this article, I’ll share some tips on how I prepare as an investor for the inevitable crash of the AI financial acrobats.
Round-Tripping Secures Nvidia’s Sales
Despite increasing competition, Nvidia has managed to maintain high GPU prices. According to my information, a server with 72 Blackwell chips (the GB200-NVL72 server) still costs around $3 million, which amounts to approximately $40,000 per GPU. This price has remained stable, with no significant erosion at the hardware level.
Nvidia fans see this as proof of the technological superiority of Blackwell chips over the competition. However, I take a slightly more nuanced view, especially since the hourly rates for using B200 GPUs “as a Service” in the cloud are definitely changing.
The prices charged by various cloud providers for B200 GPUs vary widely, indicating a highly competitive market at the Nvidia customer level.
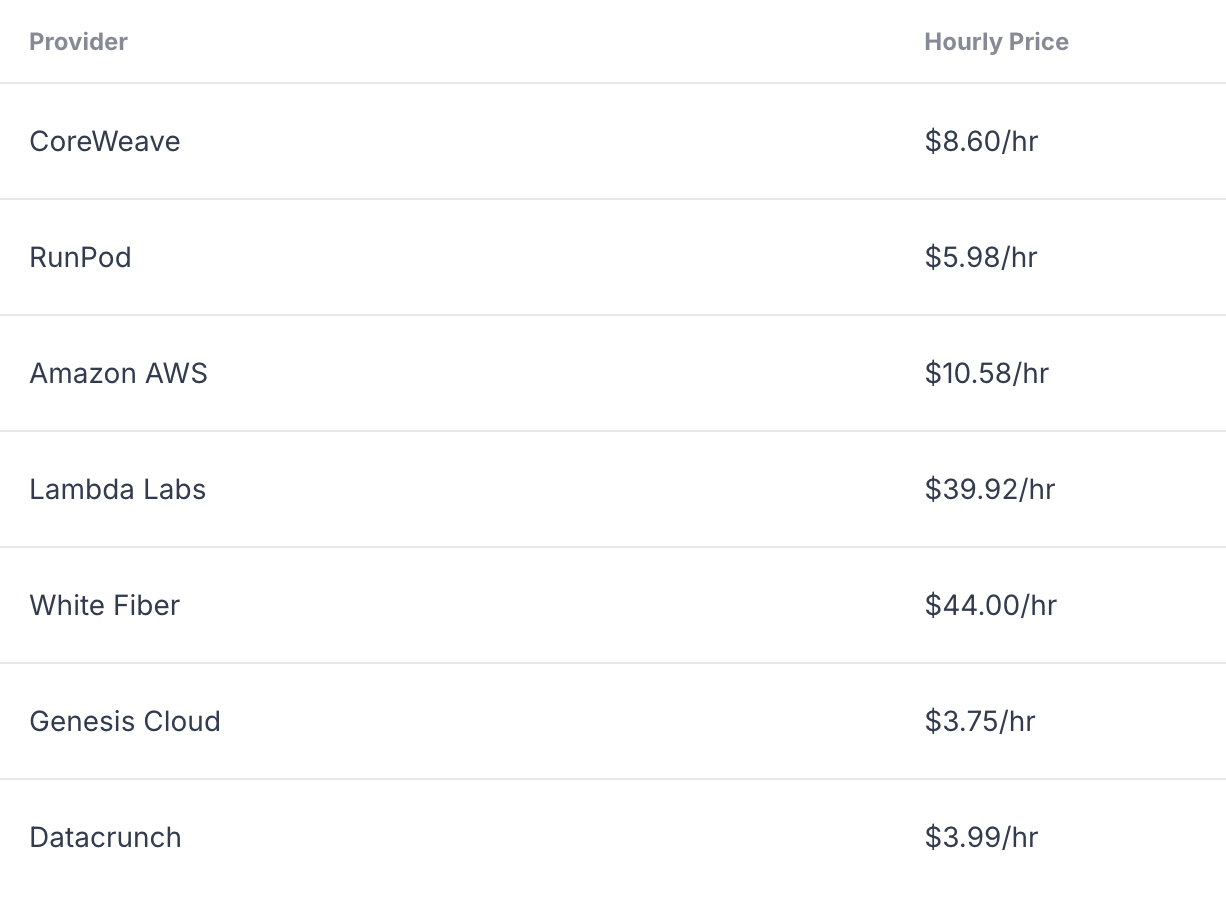
So Nvidia continues to sell its hardware to cloud providers at stable, scarce prices, while some providers compete for customers by offering much lower prices.
How does that add up? I don’t know.
What we do know is that Nvidia has further expanded its already substantial margins in recent quarters, much to the delight of its shareholders. In the last quarter, Nvidia’s operating profit was 61% of revenue. There is no sign of margin pressure.
In my opinion, however, this is due not only to a monopoly-like market position resulting from superior technology, but also to brilliant financial engineering, which the bears refer to as “round-trip” business logic.
In other words, Nvidia uses its high cash inflows to invest in its customers, encouraging them to continue buying Nvidia chips at high prices. This is nothing new. But this questionable business model takes on a new dimension when Nvidia guarantees to purchase unused AI capacity from cloud providers, vouch for their businesses, and lease back its own chips in a “lease-back” deal.
Here are a few concrete examples:
1) CoreWeave with Nvidia Backstop
Nvidia has been a CoreWeave shareholder since 2023. (See my article, “CoreWeave IPO: A Ticking Time Bomb”). CoreWeave buys Nvidia hardware on a large scale and leases it primarily to OpenAI and Microsoft. On September 15th, 2025, CoreWeave closed the circle. Nvidia committed to purchasing up to $6.3 billion in unsold cloud capacity by April 2032, effectively acting as a backstop for CoreWeave.
In other words, Nvidia acts as a financial safety net for CoreWeave, aiming to cover potential losses, boost investor confidence, and ensure stability in transactions. For Nvidia, this means it can secure sales of its GPUs at high prices today and, under certain circumstances, pay for computing hours later. For CoreWeave, it is a sales guarantee beyond its two major customers.
2) Lambda - “Leasing back” its own GPUs
In early September, Nvidia announced that it would lease 18,000 GPUs from Lambda for $1.5 billion. Interestingly, Nvidia had previously sold these systems to Lambda. This means that Nvidia generated revenue today while incurring leasing expenses in the future. Nvidia is also an investor in Lambda. Strategically, with this move Nvidia is strengthening another “Neocloud” partner that purchases Nvidia chips.
3) OpenAI: Partner, Customer, and now Shareholder
On September 22nd, 2025, Nvidia and OpenAI announced a significant letter of intent. OpenAI plans to build its own data centers and introduce at least 10 GW of Nvidia systems (Vera Rubin generation). 10 GW would be enough to supply several large cities with electricity! For further context, Microsoft’s huge Azure cloud division had a capacity of approximately 5 GW in 2023.
These OpenAI data centers could cost $500-$600 billion, a staggering $350-$450 billion of which is budgeted for Nvidia equipment.
Nvidia plans to invest up to $100 billion in OpenAI in parallel with delivering the chips. To enable financing, OpenAI will reportedly lease the chips from Nvidia instead of purchasing them.
This links OpenAI’s demand for Nvidia systems with Nvidia’s investment in OpenAI - exactly the kind of “circular” financing that observers see as a potential driver of the AI boom and, at the same time, a risk factor.
Creative Financing at OpenAI and Co.
The financial burden on OpenAI will be reduced by leasing server chips from Nvidia, but nevertheless they already forecast a cash burn of $115 billion by 2029 due to high computing costs.
The huge planned leasing deal between Nvidia and OpenAI will be structured to minimize risks for Nvidia. For example, Nvidia could set up a company that borrows money to purchase the servers and uses the chips as collateral. OpenAI’s leasing payments could then be used to repay the loan.
Other data center operators have also been looking for creative ways to finance the enormous costs of Nvidia hardware for some time. In recent years, several operators have financed their facilities in part by using Nvidia chips as collateral for loans worth billions. According to the Financial Times, since 2024 GPU-backed financing has created a new $10 billion-plus debt market for “Neoclouds” such as CoreWeave and Lambda. In addition to banks such as Macquarie Group, private credit firms like Blackstone, PIMCO, Carlyle, and BlackRock are active lenders in this market.
Do words like “GPU-backed financing” set off alarm bells for you, too? How did anyone come up with the idea that Nvidia GPUs would retain their value for many years and serve as collateral for long-term loans? It’s all a mystery to me.
Despite the potential acceptance of GPUs as collateral, OpenAI would have difficulty raising money from these lenders to purchase Nvidia chips, as the lenders would question OpenAI’s ability to finance the purchase in the long term, given the company’s projected cash burn.
So a leasing deal with Nvidia may be the only viable option.
Will OpenAI be the most valuable company on the planet in 10 years? Or will Sam Altman orchestrate the biggest bankruptcy the world has ever seen?
I wouldn’t want to underestimate Sam Altman. But, with all due respect, I still assume that he doesn’t have a viable plan for how OpenAI can ever become profitable.
For that reason alone, I wouldn’t invest in OpenAI, either before or after an IPO. The risk of a crash is enormous. Sam himself said in an interview a few weeks ago that we are in the midst of an AI hype, and many investors will lose a lot of money.
