

Due to popular demand, I am offering my stock analyses in both English and German (DE). If you would prefer to read this article in German, click here. If you would like to receive the German articles by email in the future, you can change the settings (notifications) in your Substack account here.
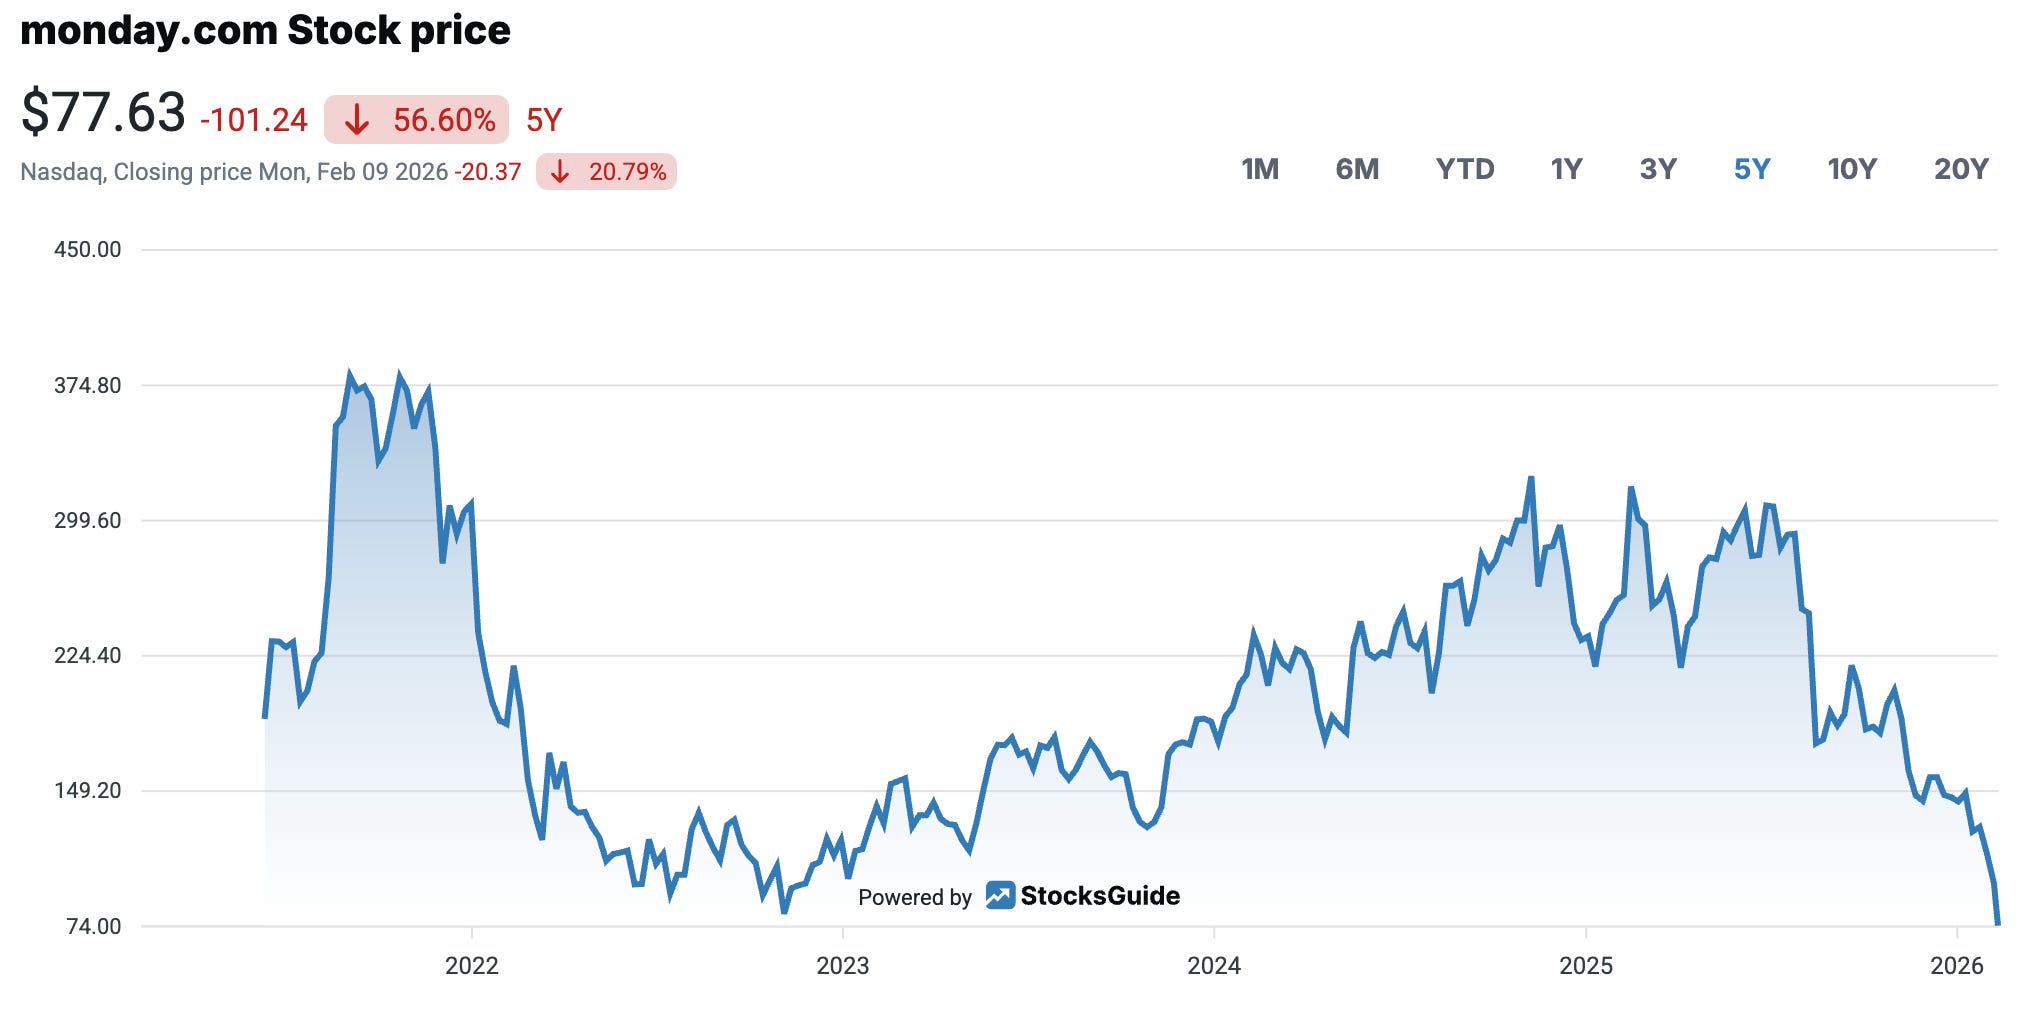
Tough times for SaaS shareholders: On February 9, 2026, Monday.com saw another sharp sell-off. Following the release of its Q4 and full-year results for 2025, MNDY 0.00%↑ shares fell again by over 20%. They hit new lows for the year and even for several years, reaching a level not seen since the end of 2022. As a result, the stock has lost three-quarters of its value over the past 12 months.
Why a SaaS company with respectable figures and healthy growth triggered such a negative market reaction can only be understood by looking beyond the bare quarterly figures and taking into account the current narrative that “AI is eating software.”
You can read what I personally think of this narrative here (now without a paywall):

However, the “market” currently believes that traditional, human-operated enterprise software is doomed, as AI agents could take over large parts of knowledge work in the future. You can think what you want about that, but as the saying goes: the market is always right.
Currently, analysts and investors (mostly from outside the industry) believe that companies such as MNDY will be disrupted and disappear into insignificance in the age of AI. There is no other explanation for the recent share price developments.
The figures for the fourth quarter of 2025 themselves were robust, especially given the difficult macroeconomic and currency environment.
monday.com results for Q4/2025 and full year 2025
Q4/2025 highlights
Revenue of $334 million represented growth of just under 25% YoY and exceeded analyst estimates.
Earnings per share of $1.04 (adjusted) and $1.45 (GAAP) were well above expectations.
Operating income (non-GAAP) was only slightly higher than the previous year at $42 million and was negatively impacted by a 20% currency loss of the US dollar against the Israeli shekel.
Free cash flow of USD 57 million (17% margin) was the weak point in the Q4 figures, as it was significantly below the USD 73 million (27% margin) in the previous year.
FY 2025 Highlights
At USD 1.232 billion, revenue was 27% higher than in the previous year.
Operating income of $175 million (non-GAAP) corresponds to an operating margin of around 14% (unchanged from the previous year).
Free cash flow amounted to $323 million (26% margin). This is offset by stock-based compensation of $177 million.
The net dollar retention rate (NRR) was 110%, two percentage points lower than the previous year.
These figures are solid, but they don’t show how well monday is really progressing on its journey from SMB business (business with smaller companies) to enterprise software business. Here are a few more data points:
41% of total revenue now comes from larger customers with an ARR (annual recurring revenue) of over $50,000 (up from 36% last year).
The NRR for large customers was 116%.
The number of customers with an ARR of over $100,000 grew by 45% to over 1,750.
Remaining performance obligations (RPO; services that have not yet been invoiced but are contractually agreed) increased by 37% to $839 million.
In short, operations continue to perform well. Monday.com is growing profitably, winning larger customers, and generating cash flow. The hard numbers normally justify a solid SaaS premium valuation for the stock due to recurring revenues.
However, investors ignored the company’s operational strength in the context of its guidance.
Why did MNDY shares crash so badly?
MNDY shares have lost 50 percent of their value in just six weeks of trading since the beginning of the year. The immediate cause may seem simple: strong results but weak future prospects. On closer inspection, however, several factors, some of which are interlinked, play a role, which I would like to discuss in more detail below:
