

Due to popular demand, I am offering my content in both English and German (DE). If you would prefer to read this article in German, click here. If you would like to receive the German articles by email in the future, you can change the settings (notifications) in your Substack account here.
So the takeover rumors surrounding PayPal have now turned into a concrete offer.
Reuters reports today that Stripe, together with private-equity investor Advent International, is offering $60.50 per PayPal share. This corresponds to an equity value of more than $53 billion and a premium of about 28% over Tuesday’s PYPL 0.00%↑ closing price. Approximately $50 billion in bank financing is reportedly already committed. Stripe and Advent would each acquire half of PayPal; a split does not appear to be part of the current offer. PayPal has not yet responded to the offer.
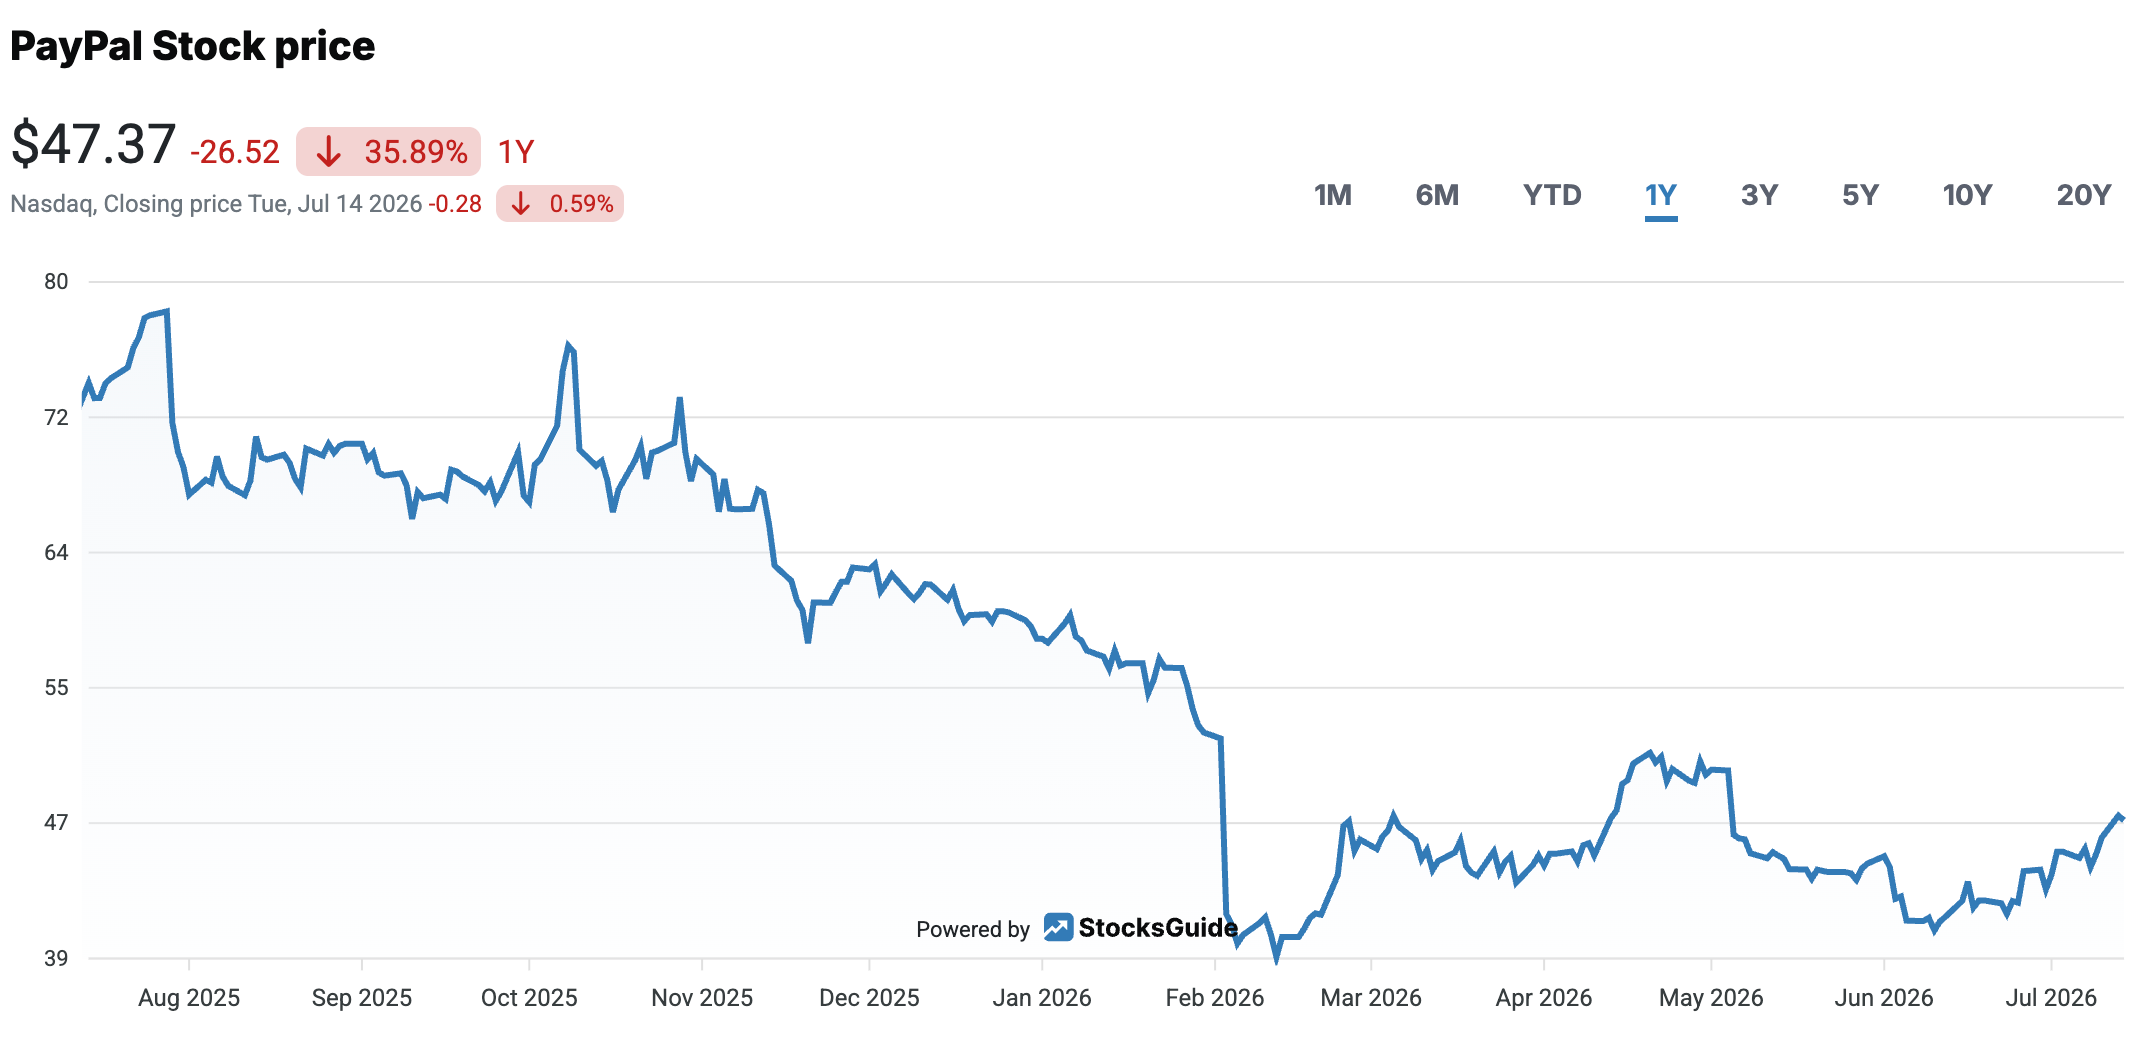
This news is particularly relevant to me because PayPal is currently the largest position in my investable model portfolio. And today’s Reuters report is a direct follow-up to my article from February:

At the time, my thesis was still speculative. Today we know: Stripe hasn’t just been casually considering PayPal. Together with Advent, a financed offer is now on the table.
How accurate was my valuation back then?
In February, I had estimated the value of PayPal’s individual components at a total of $41 to $71 billion as part of a sum-of-the-parts analysis. Based on the number of shares at the time, that corresponded to roughly $46 to $80 per share - explicitly excluding any additional control premium.
The current offer of $60.50—or just over $53 billion—falls almost exactly in the middle of that range. So my assessment at the time was neither excessive nor too conservative. It hit the range in which the actual offer is now being made with surprising accuracy.
However, there is one crucial point: The $60.50 is not a normal market value for a minority shareholder. Stripe and Advent want to take control of PayPal, its cash flows, its technology, its customer relationships, Venmo, and its large merchant network. For this, a significant control premium is typically paid.
