

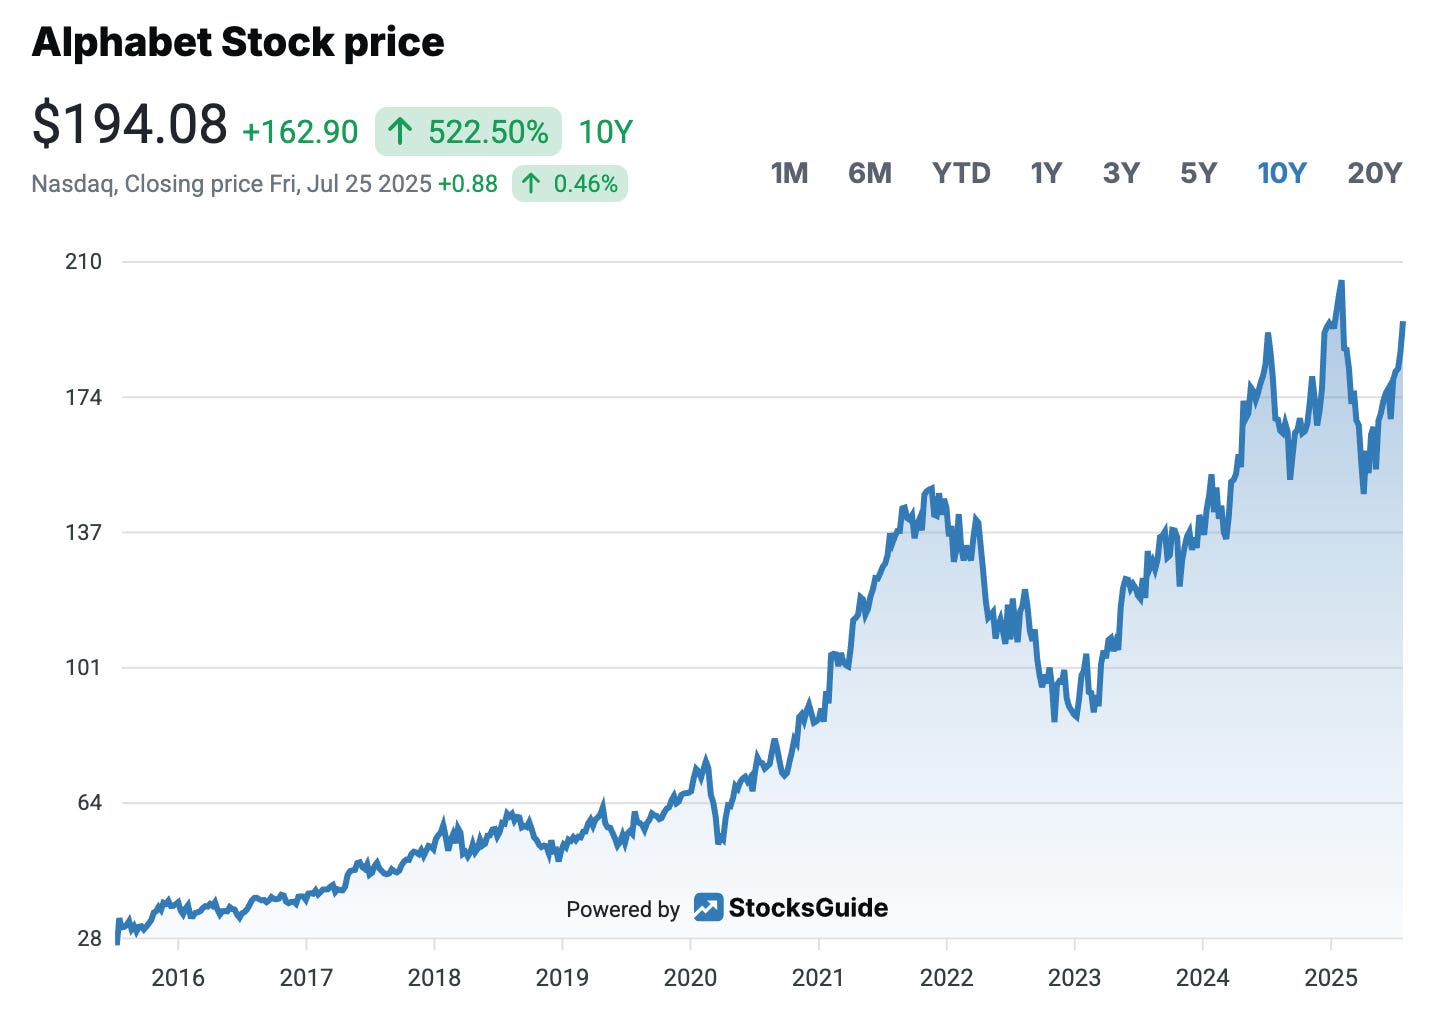
Google parent Alphabet has been the only big tech stock in my High-Tech Stock Picking portfolio for quite some time now. In my last article on the stock in October 2024 (read here), I explained why I had taken profits at the time. Since then, I have only held a relatively small position in Alphabet shares, which I would like to review today in light of the Q2 2025 results.
The Alphabet figures for Q2 2025
It is amazing how steadily Alphabet continues to grow double-digit and very profitably across all segments in the ongoing transition to the AI age.
Alphabet reported Q2 2025 revenues of USD 96.4bn (+14% YoY) and an operating profit of USD 31.3bn (+14% YoY) with an unchanged margin of 32.4%. Earnings per share rose to USD 2.31 (+22%) and significantly exceeded consensus expectations.
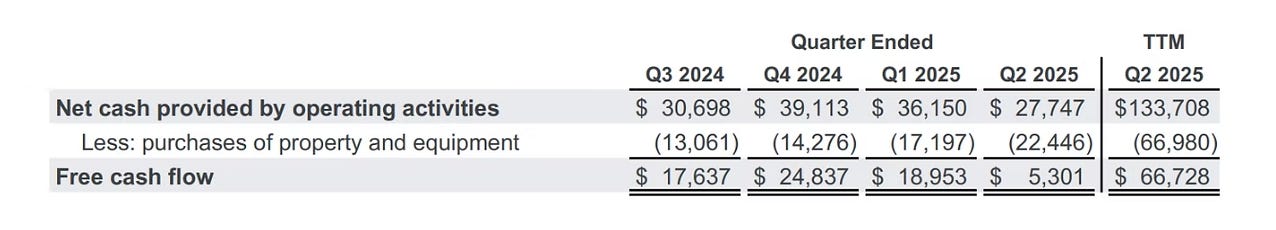
The downside of the figures: free cash flow (FCF) fell from USD 13.5 billion to just USD 5.3 billion (-60% YoY) due to exploding investments in the AI infrastructure compared to the same quarter of the previous year - but more on this later.
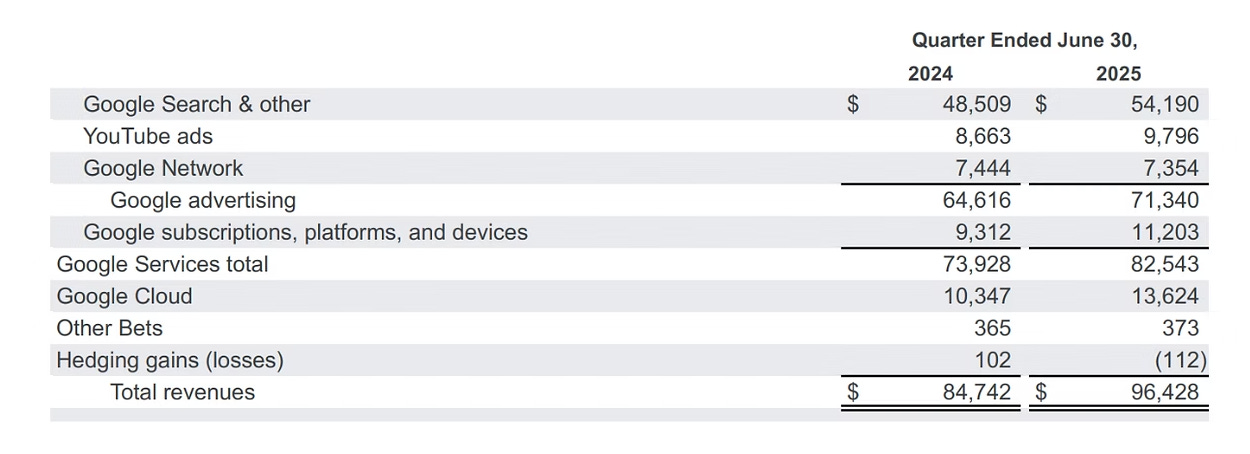
Here is an overview of the development of the segments:
Google Services
Google Search and YouTube Ads are once again showing double-digit growth. Over 120 million paying subscribers to YouTube and Google One are now also making a noticeable contribution to revenue. Google One was originally introduced as a pure storage upgrade for Google Drive, Gmail and Google Photos. However, it has since developed into a more comprehensive premium service for Google users, which includes Google Meet and Google Workspace, including AI functions. The operating margin of Google Services is an outstanding 40%.
You may be wondering how it is that Google's search revenue continues to grow, even though organic clicks on many publisher websites are falling in times of AI overviews. That sounds paradoxical at first. However, Google's Chief Business Officer Philipp Schindler emphasized: “We see monetization at roughly the same level”, despite AI overviews.
In fact, this paradox can be easily resolved: falling free traffic is forcing brands to plan more budget for paid search ads. Industry reports (e.g. from Tinuiti) show that higher costs per click increase sales on Google Search.
So far, the change in search behavior due to AI has not affected Google. The big question remains whether this will remain the case in the long term or whether new AI-based search engines from OpenAI or Perplexity will be able to successfully attack Google's core business in the future
Google Cloud
With 32% growth (and now accounting for 14% of revenue), Google Cloud's business is accelerating for the third quarter in a row. Management cites a record number of deals over USD 1 billion and points to the strong demand for its AI stack Gemini.
It is particularly impressive that the cloud margin has doubled to 21% within a year and is set to expand further towards 30% - the level of Microsoft is therefore within sight.
Other Bets (Waymo and others)
Robotaxi provider Waymo continues to expand and is now regarded as the absolute leader in the (western) world of autonomous driving. However, Waymo continues to burn through more than USD 1 billion per quarter on a turnover of just over USD 300 million. These figures clearly show how difficult it is to successfully scale a robotaxi operation.
Waymo is therefore experimenting with different business models in various cities. In Austin and Atlanta, the Waymo One service has been made explicitly available via the Uber app - based on a formal partnership. Users there can use the Uber app to drive autonomously: Waymo provides the vehicles, while Uber is responsible for dispatch, fleet management and operations. In Phoenix, Los Angeles and San Francisco, on the other hand, the service can be booked directly via Waymo One, without an Uber connection.
It will be interesting to see which business model Waymo chooses in the future. In any case, profitability of the robotaxi business is still a long way off.
What is behind the slump in free cash flow?
While Alphabet's operating profit, together with revenue, is rushing from one record to the next, cash flow is a completely different story:
It is true that operating cash flow of US$ 27.7 billion in Q2 2025 was slightly higher than in the same period last year. However, capital expenditure (CapEx) exploded to USD 22.4 billion. This is 70% more than in the previous year and the highest quarterly figure in the company's history.
Around two-thirds of this is spent on data centers and a steadily growing stock of TPU clusters, which are required for the operation of Google AI. The remainder is spent on fiber optic networks and server upgrades. Alphabet raised its annual CapEx guidance from an already record-breaking $75 billion to $85 billion. Is this really “a one-off wave of investment to meet the AI demand of the next decade”, as CFO Ruth Porat put it back in early 2024?
The bottom line for Alphabet in Q2 2025 was therefore “only” a comparatively weak free cash flow of USD 5.3 billion or an FCF margin of 5%.
What does this mean for Alphabet's shareholders?
In the short term, Alphabet has much less cash available to use for share buybacks or dividends due to the FCF slump. The cash conversion rate (TTM) has fallen from around 100% to 60% and is likely to fall further in the coming quarters, i.e. for every dollar of reported profit there is now only around $0.60 of free cash flow.
In the medium term, these investments will define the strategic clout of Google Cloud in the battle for AI workloads - those who cut back now risk losing market share. The risk here is difficult to assess: if the demand for AI computing power is not as high as expected in the next decade, the AI infrastructure in the data centers, which was procured at the current high prices, would have a correspondingly negative impact on profits through even higher depreciation.
The corresponding balance sheet item “Net Property, Plant and Equipment” has literally exploded by $53 billion to $217 billion in the past 12 months alone. The corresponding ROI should flow back via the cloud division in the long term. Always assuming that the demand for AI workloads develops as hoped and the targeted 30% cloud margins are achieved.
Valuation of Alphabet Stock Compared to Microsoft
If you have been following this substack for a while, then you know that a reasonable valuation based on free cash flow is fundamentally very important to me for any investment.
VALUATION MATTERS!
This is often forgotten in the current AI hype ;-)
If you look at the price/earnings ratio alone, Alphabet shares appear to be fairly valued with a P/E ratio of 20. The free cash flow multiple of 29, on the other hand, does not look attractively priced to me.
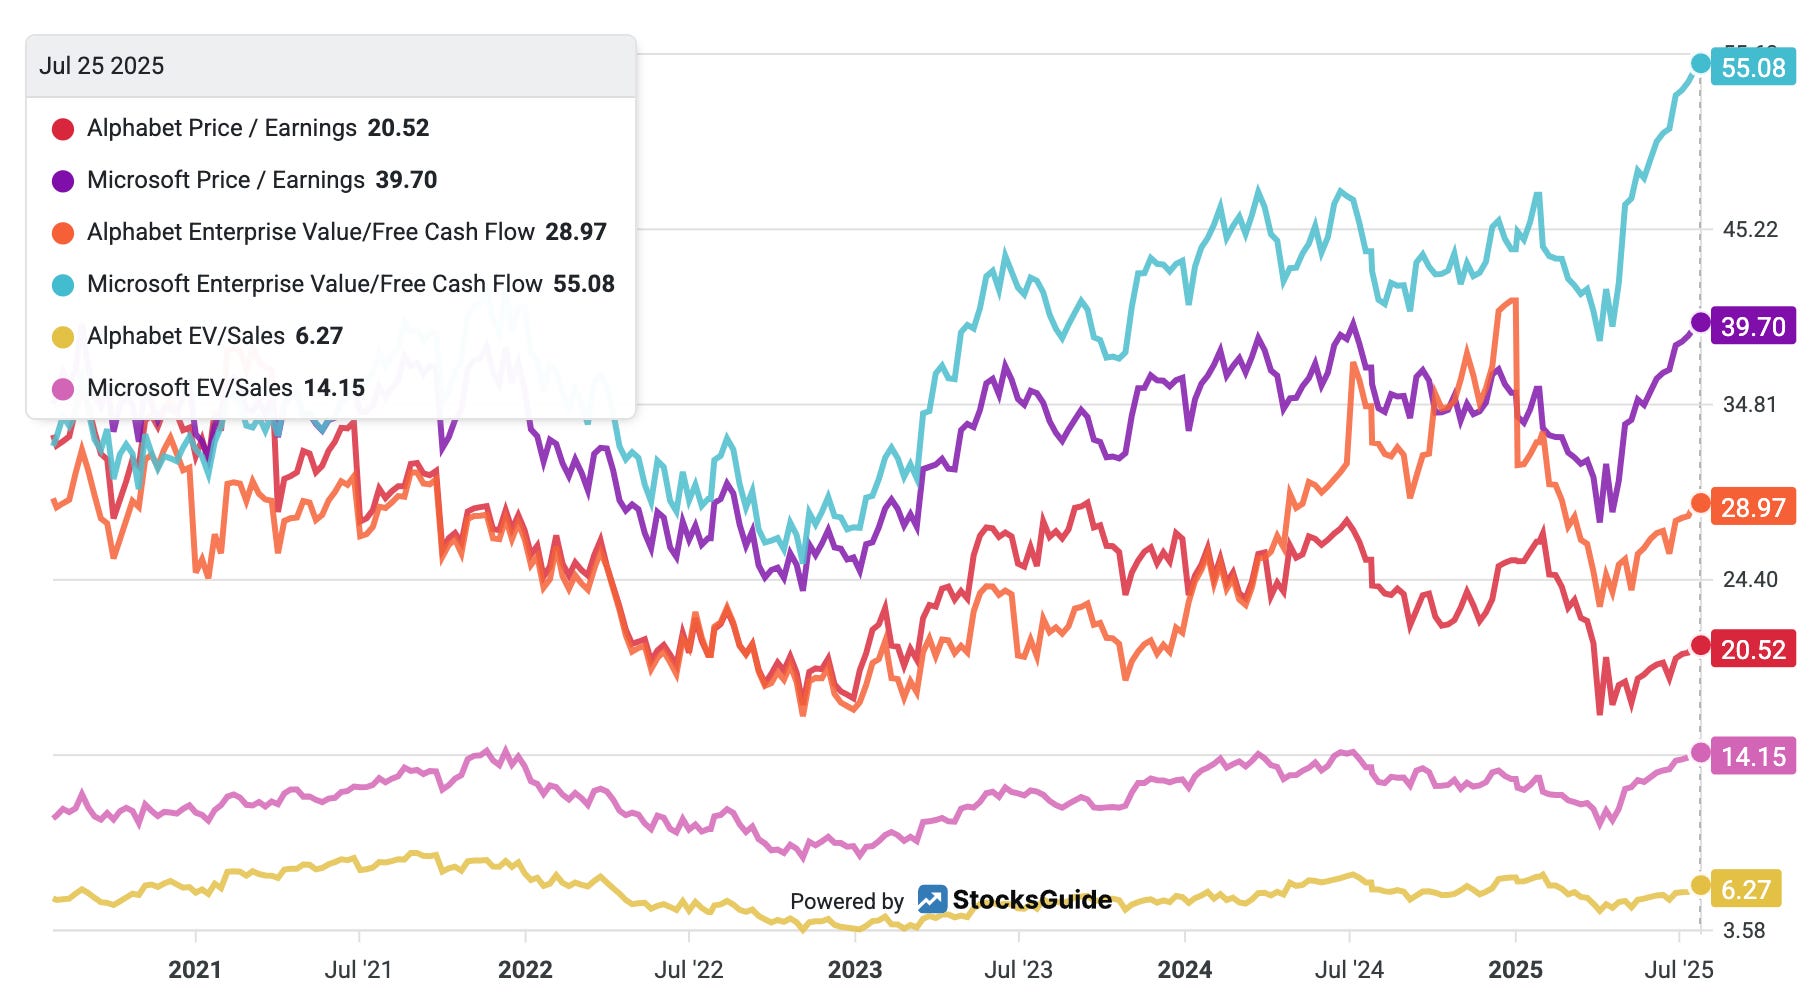
However, Microsoft shares are even more expensive. All valuation ratios are around 100% higher for Microsoft than for Alphabet. Every single dollar of Microsoft's revenue/profit/cash flow is therefore paid twice as much by the stock market as Alphabet's revenue/profit/cash flow.
There has always been a certain valuation premium in this comparison, as Microsoft's business model as a pure software company has always been more attractive than the advertising-financed Google model. However, the valuations of the two tech giants could well converge in the longer term in the age of AI if Google Cloud's margins actually approach Microsoft's high margins.
Conclusion
Alphabet once again demonstrated the strength of its two-legged business model in the first half of 2025: The company seems to be weathering the threat of AI disrupting its advertising business well and its cloud platform is growing rapidly, driven by AI. In the short term, however, upgrading the data centers is eating up almost the entire cash flow - a picture that is likely to increasingly scare off value investors.
My opinion as a growth investor: If you have five years to spare, Alphabet shares continue to offer the most attractive mix of market position, innovative strength and moderate valuation in the entire hyperscaler universe. If big tech, then Alphabet please.
For me, Alphabet shares therefore remain a holding position in my portfolio, but I am not currently planning to add to my position, which was reduced in 2024, at current prices.
If you'd like to follow Alphabet in the future together with me, please subscribe to my free Substack here:
*Disclaimer: The author and/or related persons or entities own shares of Alphabet. This post is an expression of opinion and not investment advice. Please note the legal information.
Interesting breakdown of their products, valuation metrics, and cap ex spending.
Thanks for the timely update!